
Trade Setup
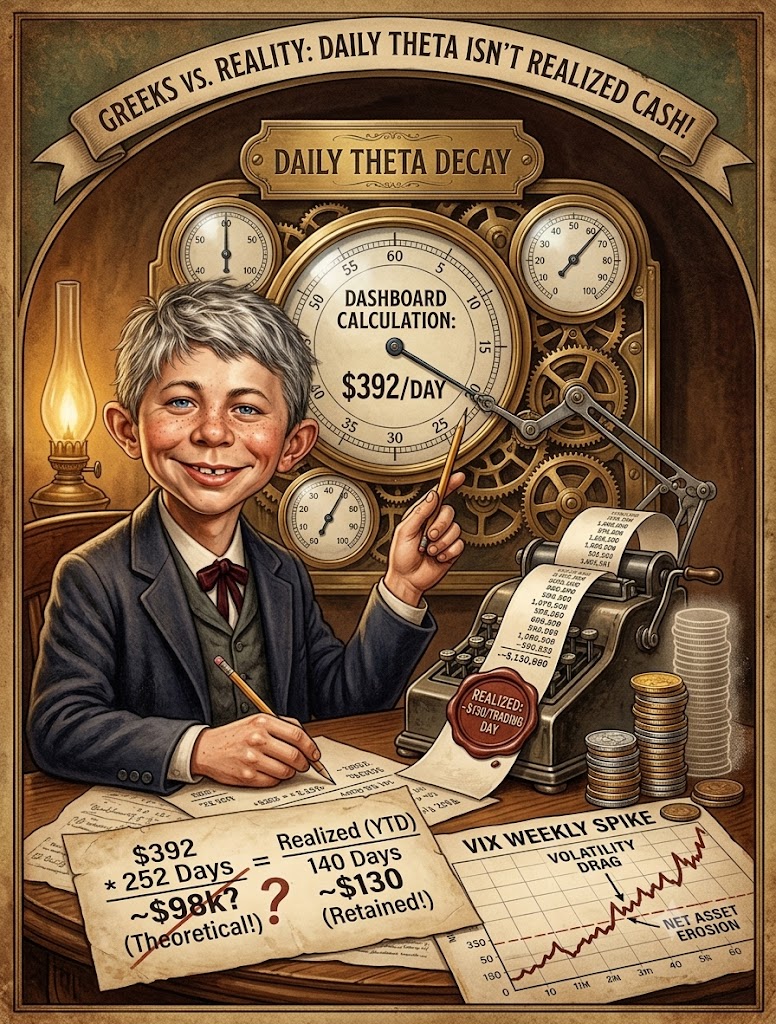
No trades were closed this week, so I am taking a global view of my accounts to review overall portfolio health, track week-over-week growth, and break down the illusion of the Greeks versus realized cash flow.

Week-Over-Week Fund Tracking
Comparing today’s snapshot against last week’s fund trackers demonstrates how passive time decay, active trade management, and mark-to-market moves impact overall account value:
- Combined Portfolio Value: Up +$5,414.31 this week ($138,865.60 today vs. $133,451.29 last week).
- Travel Fund (Individual Account): Grew from $55,420.32 to $56,828.99 (+$1,408.67). Total YTD realized profit reached $10,020.22, officially crossing the $10,000 YTD goal.
- IRA Fund (Roth IRA): Grew from $78,030.97 to $82,036.61 (+$4,005.64).
Weekly Market Context: Indices & Volatility (VIX)
Looking across the broader market, this week brought noticeable weakness and jittery sentiment across major benchmark indices. The tech-heavy Nasdaq Composite and S&P 500 slipped as heavy megacap earnings raised investor concerns over high AI infrastructure spending. Concurrently, energy market pressures and geopolitical friction pushed crude oil higher earlier in the week.
This index drag triggered a sharp jump in market volatility. The CBOE Volatility Index (VIX) surged from its mid-15 baseline up toward the 19–20 level before settling near 18.80. For option sellers, this volatility spike expands option premiums (Vega expansion). While a higher VIX increases future credit potential, it also temporarily inflates short option values, creating mark-to-market friction even as time decay passes.
When looking at a platform like tastytrade, it’s easy to get hooked on shiny metrics. Option Greeks—specifically Theta—make it look like you’ve built a machine dropping passive cash into your account every 24 hours. But comparing theoretical daily decay against actual realized wallet returns gives you a much clearer picture of how options mechanics work in reality.
Strategy Application
If you sell options, Theta is usually your best friend. It measures time decay—the rate an option loses extrinsic value simply as the calendar advances. Looking at this account snapshot, the dashboard displays impressive numbers on paper:
- Theoretical Daily Decay (Theta): $392 a day
- Total Time Value Left to Collect (Extrinsic): $9,136
- Actual Money Made So Far This Year (P/L YTD): $18,224.82 (across 140 elapsed trading days)
If you do simple back-of-the-napkin math and multiply that $392 a day by a full trading year (252 days), it looks like you’re on track to make nearly $98,000 just sitting on your hands.
Theoretical Paycheck ($392/day)
  ├── Minus: Normal price movement friction (Delta/Vega drag)
  ├── Minus: Realized trade losses (Adverse market risk)
  ├── Minus: Taking profit early (Managing at 50%)
  └── Equals: Realized Profit (~$130.18/day)
In the real world, you don’t keep every penny of that $392. If you divide the $18,224.82 actually earned so far by the 140 trading days we’ve had this year, the actual paycheck comes out to about $130.18 a day.
Why Theta is Theoretical (Dashboard Math vs. Wallet Math)
To understand where that gap comes from, you have to look at how option pricing models calculate time decay:
- The “Frozen Market” Fallacy: Pricing models calculate Theta under the assumption that asset prices and implied volatility stay completely still. In reality, market prices fluctuate constantly (Delta), and volatility expands or contracts (Vega). A sharp move against your short strike or a sudden VIX spike can temporarily erode days of passive time decay in seconds.
- Active Trade Management: Theta calculations assume every contract is held all the way to expiration until it hits $0.00. In practice, disciplined options traders rarely do that. Closing a short position early at a 50% profit target or exiting a challenged spread removes that trade from the board. You willingly surrender remaining theoretical Theta to take risk off the table and free up capital.
- Non-Linear Decay Curves: Theta is not a static daily wage. Time decay follows a curve that accelerates rapidly as expiration approaches. Because positions are constantly being opened, closed, or rolled across different expiration cycles, daily portfolio Theta is a dynamic snapshot, not a fixed guarantee.
- The Realized Capture Ratio: Historical trading data shows that systematic short option sellers typically realize roughly one-third to one-fourth of their open theoretical Theta as retained profit over a large sample size. The rest is consumed by market friction, defensive adjustments, and price swings.
Risk Profile
The variance between theoretical daily Theta ($392/day) and actual realized cash flow ($130.18/day) comes down to capital deployment, active trade management, and structural market exposure:
- Adverse Market Risk & Realized Losses: Theoretical Theta assumes zero losing trades. In reality, options trading is not a risk-free yield generator, and taking losses when market moves breach your parameters is an inevitable cost of doing business. When a trade goes wrong and you close it for a loss to protect capital, that dollar loss directly subtracts from your accumulated pool of prior Theta gains. A single $500 loss on a challenged position wipes out over a full day’s worth of theoretical portfolio decay, dragging the gross $392/day down to the true $130.18/day net outcome.
- Capital Deployment & Account Strain:
- In the Travel Fund (Individual Account), buying power usage sits at 44.2% ($25,100 tied up out of $56,828 NetLiq). This conservative allocation leaves a healthy cash cushion to absorb adverse market moves without stress.
- In the IRA Fund (Roth IRA), buying power usage sits at 88.0% ($72,216 tied up out of $82,036 NetLiq). This account is heavily leveraged. High capital utilization drives higher daily Theta ($248 vs. $144), but leaves very little cash buffer if margin requirements expand during market pullbacks, forcing faster defensive actions.
- Directional Bias (Delta & Volatility Risk): Theta models assume markets stand still. Notice the 72 Delta in the IRA Fund versus -1 Delta in the Travel Fund. The IRA Fund leans noticeably bullish, meaning a sharp market pullback creates directional losses that offset daily time decay.
Expected Outcome
Understanding the distinction between theoretical metrics and realized cash flow keeps expectations grounded in mechanical reality:
Capital Efficiency: On a combined portfolio value of $138,865.60, retaining roughly one-third of theoretical daily Theta delivers an annualized return of ~23.6%, proving that full Theta capture isn’t required to drive steady account growth.
Speedometer vs. Odometer: Daily Theta acts like a car’s speedometer. A $392 Theta readout indicates your portfolio is currently cruising at a theoretical rate of $392/day. Realized cash flow is your odometer—it measures the net distance traveled safely after factoring in speed reductions, turns, and bad weather.
Realized Pace: Maintaining an average realized pace of $130.18 per trading day projects out to roughly $32,800 in net profit across a standard 252-day trading year.