
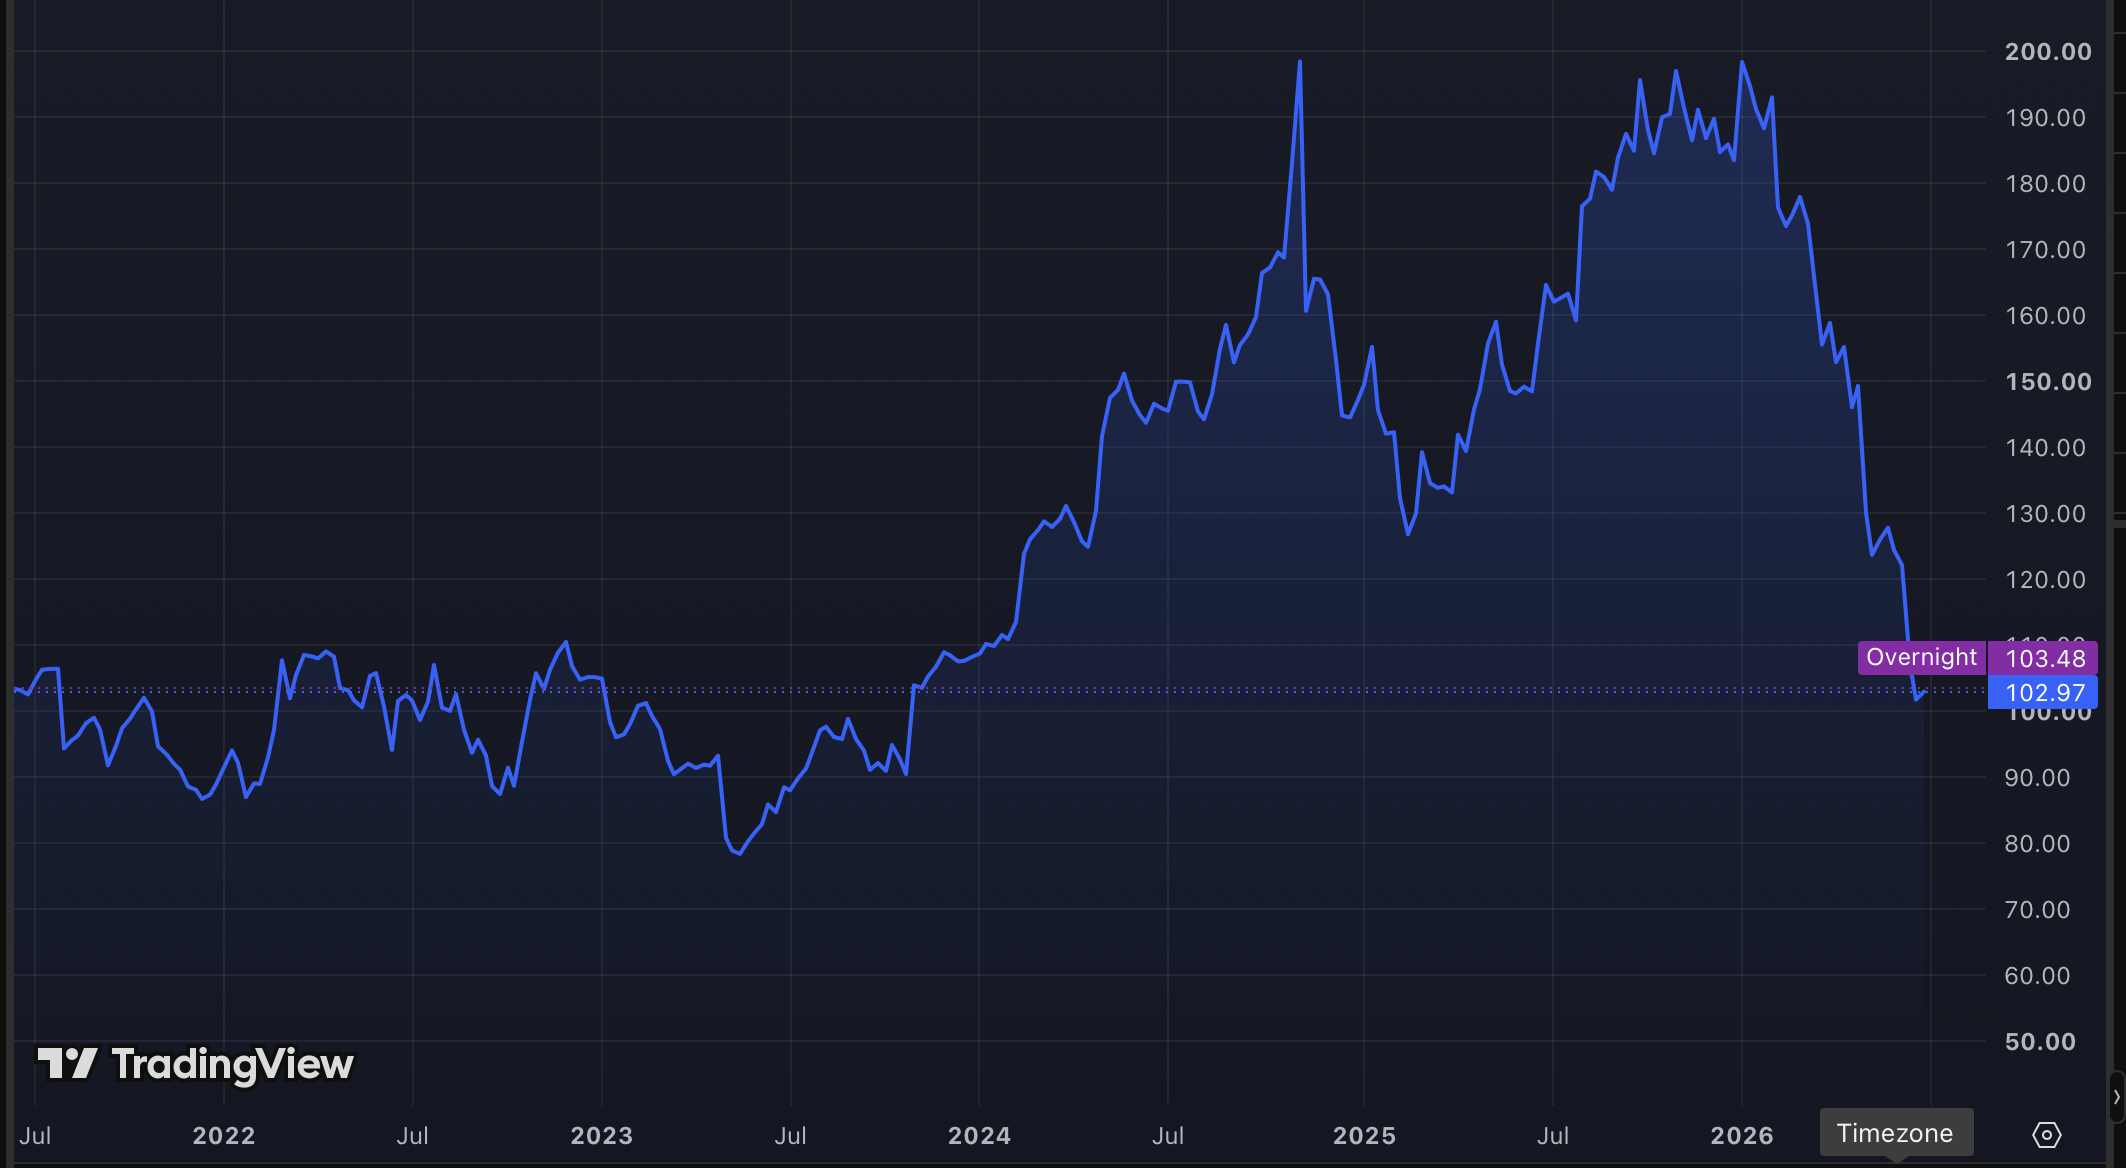
Investment Rating Section
Investment Rating:
BUY (High-Conviction Value Opportunity)
The Verdict:
Leidos represents a highly resilient, recession-proof government IT powerhouse trading at a rare, single-digit Owner Earnings multiple due to an overblown market panic over near-term government efficiency cuts.
Current Market View:
The market is currently pricing Leidos as if its federal revenue backlog is facing an imminent structural collapse, ignoring the highly recurring nature of its mission-critical IT programs.
Valuation Framework:
10-11x normalized trailing Owner Earnings.
Fair Value & Investment Range
| Metric | Estimate |
| Current Share Price | ~ $102.97 |
| Current P/E Multiple | ~ 9.42x |
| My Fair Value Range | $126 – $139/share |
| Attractive Buy Zone | $105 – $125/share |
| High-Conviction Opportunity | Below $105/share |
| Valuation Framework | 10-11x normalized Owner Earnings |
| Margin of Safety Needed | 20-30% discount to Fair Value |
Note: My Fair Value Range mathematically aligns exactly with the price range generated in Scenario 2 of the valuation section.
Investment View
The question is not whether the company is good — the question is whether the current price offers an equity coupon rate high enough to satisfy a disciplined value investor. At $102.97 per share, Leidos is trading at a microscopic 8.14x Price-to-Owner-Earnings (P/OE) ratio, offering an implicit cash yield that far outstrips the broader market’s bloated multiples.
This business is an elite, capital-light government systems integrator that acts as the central nervous system for the U.S. Department of Defense, civil agencies, and national intelligence. Over 90% of its revenues are derived directly from the federal government, backed by a massive $48.40 billion backlog that guarantees years of predictable cash generation.
By compressing the stock to a single-digit earnings multiple, the market has handed value investors a massive margin of safety. We are purchasing a recession-proof government annuity at a deep cyclical-bottom price, insulating us against permanent capital loss while setting up an asymmetric path to double-digit annualized returns.
Fair Value Uncertainty
Fair Value Uncertainty: Low
The uncertainty is not primarily about:
- Business durability: Leidos is deeply embedded in the federal apparatus, and its software architectures cannot be extracted without risking national security infrastructure.
- Competitive position: It is the largest provider of federal IT services, enjoying scale advantages that lock out smaller software competitors.
- Revenue stability: Its massive multi-year backlog and high customer retention rates provide unparalleled revenue visibility.
The main variables are:
- Government efficiency initiative execution, which could temporarily slow down new contract award cycles.
- The timeline of fixed-price contract integrations, specifically within the recently acquired Entrust business.
- Working capital volatility, which occasionally delays quarterly cash collection cycles.
Investor Watch Point
What price or event would change the investment thesis?
A sustained drop in the company’s book-to-bill ratio below 0.90x over three consecutive quarters would indicate structural headwinds in contract renewals. Additionally, any aggressive, debt-fueled mergers and acquisitions outside of their core IT competencies would warrant a re-evaluation of management’s capital allocation discipline.
Investment Snapshot
| Metric | Current View |
| Company | Leidos Holdings, Inc. (LDOS) |
| Business Description | Premier technology and engineering solutions provider specializing in defense, intelligence, civil, and health markets for the U.S. government. |
| Market Cap | ~ $12.95 billion |
| Current Share Price | ~ $102.97 |
| Current P/E | 9.42x |
| Forward P/E | 8.31x |
| P/Owner Earnings (P/FCF) | 8.14x |
| Owner Earnings Yield | 12.3% |
| Dividend Yield | 1.7% |
| IV Rank | 95.6% |
| Implied Volatility | 97.0% |
| Wall Street Consensus Target | $172.00 (Sentiment: Neutral / Bearish) |
| Value Investor Target Multiple | 10-11x Owner Earnings |
| Initial Buy Zone | $105 – $125/share |
Investment Thesis
Leidos Holdings, Inc. came across my radar because of a dramatic disconnect between its raw cash generation capabilities and its sudden share price collapse. The stock has been hammered by a wave of short-term institutional panic, pushing the implied volatility rank (IVR) to a staggering 95.6% and implied volatility (IV) to 97.0%.
While momentum traders are fleeing because of superficial fears surrounding federal government restructuring and budget showdowns, they are completely missing the physical reality of the business. The Department of Defense cannot simply turn off its modern digital command systems, cybersecurity networks, or health portals.
For the contrarian value investor, this short-term panic is a textbook gift. We are buying a capital-light compounding machine at a structural discount, directly capitalizing on the career-risk fears of mainstream Wall Street analysts who cannot afford to hold a temporarily out-of-favor stock.
Business Quality: The Digital Gatekeeper to Federal Spending
Leidos is not a hardware-heavy manufacturing business; it is an elite, capital-light systems engineering firm. It acts as the primary tech-consultant and software architect for the government, designing everything from air traffic control systems to AI-driven datasets for military battlefield intelligence.
The economic moat here is anchored by intense customer switching costs and systemic career risk. For a government procurement officer, choosing an unproven startup over Leidos to manage a critical intelligence database is a massive career hazard; Leidos is the safe, established choice that “never gets fired.”
Because Leidos primarily deploys high-end engineering labor rather than heavy physical machinery, its business model requires virtually zero capital reinvestment to grow. This capital-light profile allows the business to convert almost all of its operating profit directly into disposable cash flow, driving historically high returns on invested capital.
Financial Strength: The Good
Revenue Growth
Leidos has demonstrated exceptionally steady growth, with Q1 2026 revenues climbing 4% year-over-year to $4.40 billion. The underlying driver is a secular, non-negotiable demand for digital modernization, cloud migration, and intelligence analytics inside federal agencies.
Free Cash Flow & Owner Earnings Machine
To find the true economic reality of this business, we must ignore GAAP net income and calculate Owner Earnings, which adjusts for non-cash distortions and maintenance capital expenditures.
We define Owner Earnings as: Net Income + Depreciation & Amortization – Average Capital Expenditures.
| Quarter | Free Cash Flow (or Net Income + D&A – CapEx) |
| Q1 2026 | $376.00 million |
| Q4 2025 | $367.00 million |
| Q3 2025 | $412.00 million |
| Q2 2025 | $436.00 million |
The company generated approximately: $1,591.00 million in trailing annualized Owner Earnings.
This immense cash machine converts over 110% of GAAP net income into pure owner cash flow. With capital expenditures averaging a tiny $31 million per quarter, Leidos displays remarkable capital efficiency, giving management immense cash flexibility to buy back cheap shares and pay down leverage.
Balance Sheet: The Strength / Weakness
| Metric | Amount |
| Cash | ~ $457.00 million |
| Total Debt | ~ $7,264.00 million |
| Net Debt | ~ $6,807.00 million |
| Debt/EBITDA | 3.05x |
| Net Debt/Owner Earnings | 4.28x |
The balance sheet reflects a temporary spike in debt used to finance the strategically vital acquisition of Entrust Solutions Group in early 2026. However, given that Leidos generates roughly $1.60 billion in annual cash flows, the debt profile is highly manageable and is expected to rapidly de-lever over the next 18 months.
The company’s negative tangible book value is not a sign of distress, but rather an accounting byproduct of successful share repurchases and premium acquisitions that created substantial goodwill.
Valuation: The Main Problem / Opportunity
| Metric | Multiple |
| P/E Ratio | 9.42x |
| Forward P/E | 8.31x |
| Price / Owner Earnings | 8.14x |
| EV / EBITDA | 8.09x |
The market is currently pricing Leidos at a pessimistic 8.14x Owner Earnings multiple. This valuation is drastically disconnected from Leidos’ historical trading range of 14-16x. Wall Street’s career-risk driven analysts have trimmed their immediate targets out of near-term fear, ignoring the company’s raised full-year guidance and highly visible backlog.
What Is The Company Worth?
Using a conservative cash-flow-to-equity framework, we map out three distinct valuation scenarios for Leidos.
Scenario 1: Premium Quality Business (Optimistic Base)
- Assumptions: Leidos easily integrates Entrust, government budgets stabilize, and the multiple rerates to its historical premium.
- Target Multiple: 12-14x Owner Earnings.
- Estimated Fair Value: $151 – $176/share.
- Explanation: The market once again rewards these highly visible, recession-proof government cash flows as defense tech spending remains strong.
Scenario 2: Attractive Entry (Conservative / Mid-Cycle)
- Assumptions: Flat to modest 3% organic growth, minor integration delays, and a conservative mid-cycle multiple.
- Target Multiple: 10-11x Owner Earnings.
- Estimated Fair Value: $126 – $139/share.
- Explanation: This serves as our comfortable baseline return, requiring no major growth assumptions to justify a significant upside from current levels.
Scenario 3: Value Investor Opportunity (Pessimistic / Cyclical Bottom)
- Assumptions: Severe margin contraction, prolonged federal spending freezes, and multiples compressed to historic lows.
- Target Multiple: 8-9x Owner Earnings.
- Estimated Fair Value: $101 – $113/share.
- Explanation: Trading at the absolute floor of defense sector valuations. Even under this severe distress scenario, the downside risk is completely insulated because the current price of $102.97 is already resting here.
What Price Would Interest Me?
Watch Zone:
- $139/share
- This represents a fair 11x Owner Earnings multiple, yielding an 9.1% equity coupon rate. At this price, the business is fairly valued but lacks a wide margin of safety.
Attractive Buy Zone:
- $105 – $125/share
- An exceptional entry point offering a 20%+ margin of safety to conservative fair value. This zone provides double-digit compounding returns with highly insulated downside.
Exceptional Opportunity:
- Below $105/share
- The current price of $102.97 sits firmly in this zone. Buying here implies a 12.3% Owner Earnings Yield on a highly defensive business, meaning the risk of permanent capital loss is extremely remote.
Additional Metrics Investors Should Watch
- Owner Earnings Growth: Check if the business continues to sequentially expand its cash collections.
- Return on Invested Capital (ROIC): Ensure ROIC remains steady above 4% as the capital-light integration of Entrust progresses.
- Capital Allocation (Buyback Yield): Watch if management capitalizes on the cheap stock price by aggressively shrinking the basic shares outstanding (which decreased 2.29% year-over-year in Q1 2026).
- Contract/Subscription Health: Monitor the book-to-bill ratio, ensuring it tracks near or above 1.0x to maintain the revenue pipeline.
Risks
- Valuation Risk: The market’s irrational sentiment surrounding federal budget efficiency cuts could keep the multiple compressed at single-digit levels longer than fundamentally justified.
- Business/Moat Risk: Delays or cost overruns on fixed-price software development contracts could temporarily weigh on operating margins.
- Capital Allocation Risk: If management chooses to pursue further debt-fueled acquisitions instead of prioritizing rapid de-leveraging or cheap share buybacks, the cash compounding thesis would weaken.
Final Takeaway
Leidos Holdings, Inc. is the type of company a long-term investor would love to own.
The business has:
[X]Competitive advantages (Systemic switching costs, elite scale, and deeply embedded software architectures)[X]Strong cash generation (Unusually robust Owner Earnings converting over 110% of net income)[X]Durable business model (Recession-proof revenue stream backed by a massive $48.40B backlog)[X]Attractive industry position (The largest systems integrator in a highly consolidated federal space)
But today’s valuation determines whether it is a good investment.
A great company does not always make a great investment at any price.
The opportunity comes when the market offers a price that provides an adequate margin of safety. At $102.97, the market has handed us an exceptional defense compounder at a deep value price.
Disclaimer: Fair value estimate based on normalized earnings multiples, Owner Earnings analysis, and margin-of-safety principles. This is not a recommendation to buy or sell securities.