
The One-Sentence Bottom Line: We are collecting a $710 credit to bet that the S&P 500 stays depressed below 6,913, effectively profiting from the “fear premium” baked into the market by the Iran conflict.
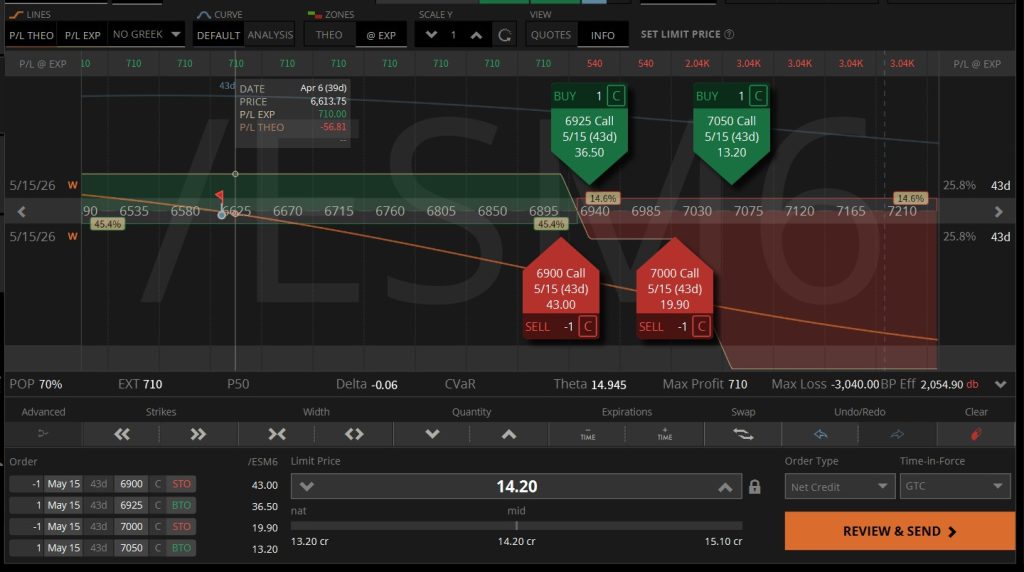
The Macro Narrative: Fading the “Goldilocks” Recovery
As of April 2, 2026, the S&P 500 is trading near 6,582.60. The market is currently grappling with a “Stagflation Storm” narrative: Brent Crude has surged toward $110 following the closure of the Strait of Hormuz, and President Trump has issued a 48-hour deadline to Iran, signaling potential escalations.
While the headlines are dire, they have pushed IVx to 24.4% and the VIX to 24.58, making far-out-of-the-money calls incredibly expensive. This trade acts as an “insurance provider” to the panic. We are wagering that the geopolitical weight and the Fed’s “delayed easing” stance (with zero rate cuts now priced in for 2026) will prevent a massive 5% recovery rally in the next 43 days. If the market stays down, moves sideways, or even drops further, we keep the full credit.
Trade Metadata
| Category | Value |
| Asset | /ESM6 (S&P 500 Futures) |
| Trade Date | April 2, 2026 |
| Current Price | 6,582.60 |
| VIX (/VX) | 24.58 |
| IVx | 24.4% |
| Expected Move | +/- 357.15 |
Execution Table: The “Inverted Tent” Structure
Expiration: May 15, 2026 (43 Days)
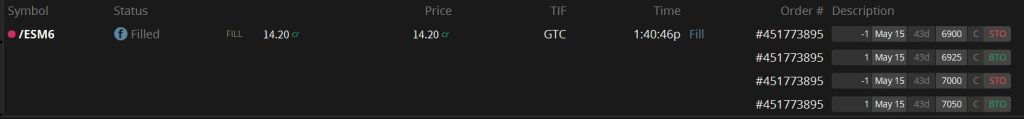
| Action | Strike | Type | Role |
| Sell 1 | 6900 | Call | The Profit Floor (Keep price below this for credit) |
| Buy 1 | 6925 | Call | Entry to Danger Zone (Loss starts here) |
| Buy 1 | 7000 | Call | Exit from Danger Zone (Loss ends here) |
| Sell 1 | 7050 | Call | The Overhead Recovery (Profit returns here) |
Financial Blueprint
| Metric | Value |
| Net Credit | $14.20 |
| Total Cash Value | $710.00 ($14.20 x $50 Multiplier) |
| Primary Profit Zone | Anything below 6,913.20 |
| Lower Breakeven | 6,914.20 |
| Theta (Daily Decay) | +$14.94 |
| Buying Power Effect | ~$2,054.90 |
| Safety Buffer | 5.02% (331.60 pts to the 6,900 strike) |
Strategic Rationale
- The Volatility Edge: By selling the 6,900 and 7,050 calls, we are capturing the “fear spike” in premiums. Buyers are overpaying for upside protection in case of a sudden peace deal; we are the ones selling them that expensive hope.
- The Greek Edge: This is a Positive Theta play. As long as the S&P 500 remains below the 6,900 level, we accrue nearly $15 in profit every 24 hours purely through the passage of time.
- Expected Move Logic: The market’s expected move is ~357 points. Our “Danger Zone” doesn’t even begin until the market rallies 317 points. We are effectively betting that the market will not realize its full bullish potential during a period of war and high oil prices.
Management Plan
- 50% Profit Target: If the trade value drops to $7.10 (capturing a $355 gain), we close the position to remove “tail risk.”
- Hard Stop: If the S&P 500 rallies to 6,850, the trade is approaching the “Inverted Tent.” We exit manually to preserve the remaining credit and avoid falling into the “Risk Pit.”
The “Nightmare Scenario”
The primary risk isn’t a crash—it’s a “Goldilocks Rally.” If the Iran conflict resolves overnight and the S&P 500 stages a perfect 5.5% recovery, it would land exactly between 6,925 and 7,000. In this “Risk Pit,” the short 6,900 call would be deeply in-the-money while the protection hasn’t fully kicked in, leading to a maximum loss of approximately $540.