
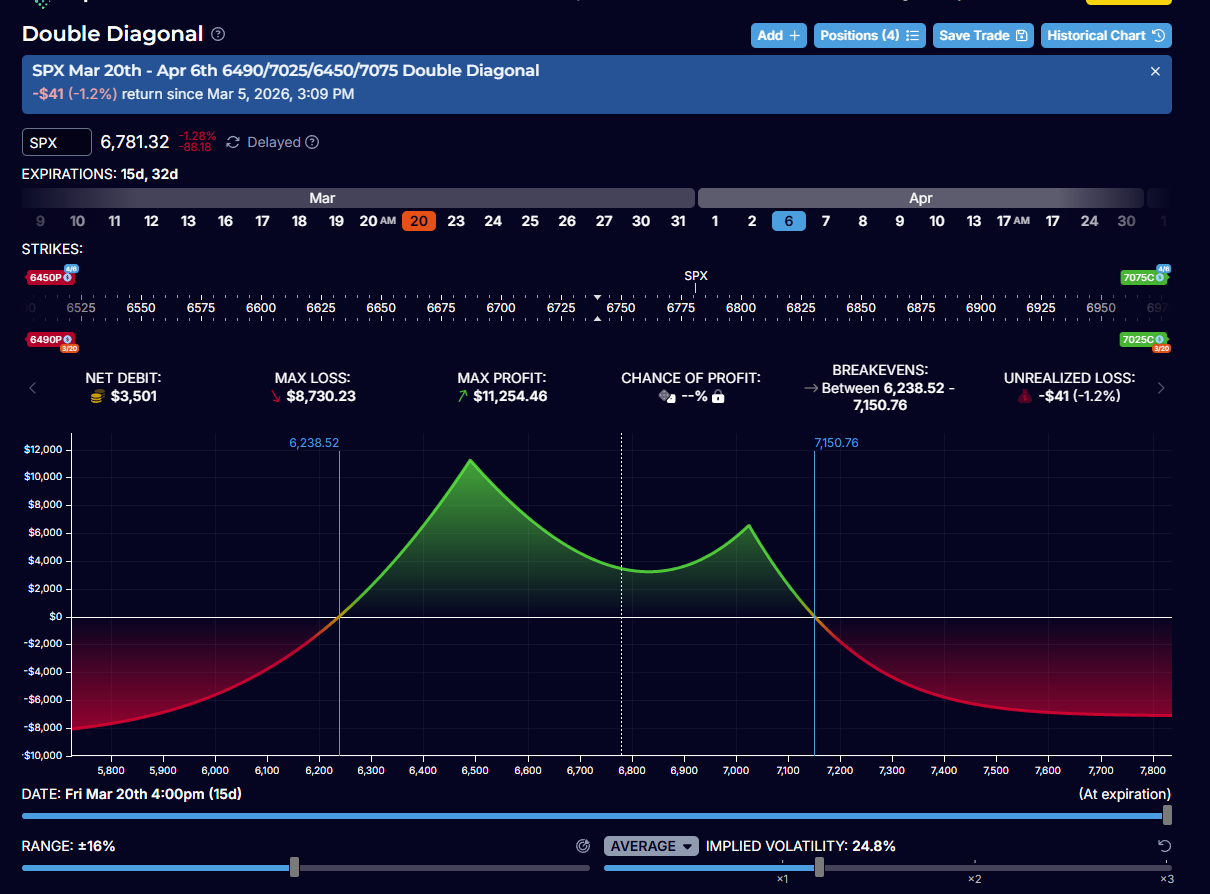
Market Date: March 5, 2026 | SPX: 6875 | VIX: 24.10
In a high-volatility environment, most traders are white-knuckling directional bets. Today, we’re looking at the Double Diagonal—a professional-grade setup that thrives on time decay and, more importantly, a rare distortion in the volatility market known as Backwardation.
The Strategy Setup
To build this “Profit Tent,” we are spreading our risk across two different expiration cycles and four different strikes.
- The Call Wing: SOLD 1 Mar 20 7025 Call / BOUGHT 1 Apr 06 7075 Call
- The Put Wing: SOLD 1 Mar 20 6490 Put / BOUGHT 1 Apr 06 6450 Put
- Net Debit: ~$3,506 per unit
Notice the Skew: We’ve given the market 385 points of room to the downside, compared to only 150 points to the upside. In a VIX 24.10 world, we respect the “elevator down” move and give the put side extra breathing room.
The “Secret Sauce”: Exploiting Backwardation
Most of the time, the market is in “Contango”—where the future is more uncertain than the present. But right now, we are seeing a volatility inversion:
- Front Month (Mar 20): 25.0 IV
- Back Month (Apr 06): 23.3 IV
This is our edge. We are selling the “Front-Month Fear” and buying the “Back-Month Discount.” By selling the expensive insurance and buying the cheaper insurance, we aren’t just trading price; we are trading the Volatility Surface. When the market calms down, that 25.0 IV will “crush” faster than the 23.3 IV, handing us a profit even if the SPX remains stagnant.
The Greeks: The Pulse of the Trade
We’ve balanced this position to be a “Sleep-at-Night” setup. According to the platform data, here is our current standing:
| Greek | Value | The “So What?” |
| Net Delta | 0.27 | Delta Neutral. We have nearly zero directional risk. We don’t care if the market moves up or down 50 points tomorrow. |
| Net Theta | +$204.84 | The Income Engine. This trade collects roughly $205 per day in “rent.” Every sunrise increases our equity. |
| Net Vega | +$465.23 | The Volatility Hedge. Unlike a standard Iron Condor, we are Long Vega. If fear spikes further, our long-dated options swell in value to protect us. |
The Discipline: Exit & Management Plan
A trade is only as good as its exit. We treat our Double Diagonals with the same rigor as our Double Calendars:
1. The Profit Target: 25%
We look to exit when the trade shows a 25% return on the debit paid (roughly $875 profit per spread). In high volatility, profits can be fleeting—don’t get greedy.
2. The Time Exit: The “48-Hour Rule”
We never hold the short Mar 20 legs into the final 48 hours of expiration.
- The Rule: Exit the entire position 2 days before the front-month expiration.
- The Reason: This avoids the “Gamma-Scythe.” In the final 48 hours, a small SPX move can cause violent swings in P/L. We harvest the “safe” Theta and leave the rest.
3. The Hard Stop: 25% Loss
If the trade goes against us and the total debit loses 25% of its initial value, we close the entire position. No “hoping” for a reversal—we preserve capital for the next setup.
Final Thoughts
This trade is a mathematical masterpiece. By maintaining a near-zero Delta (0.27) and a massive Theta ($204), we’ve turned the passage of time into a paycheck. But the real win is the Volatility Arbitrage: selling overpriced panic and buying discounted protection.
Leave a Reply