
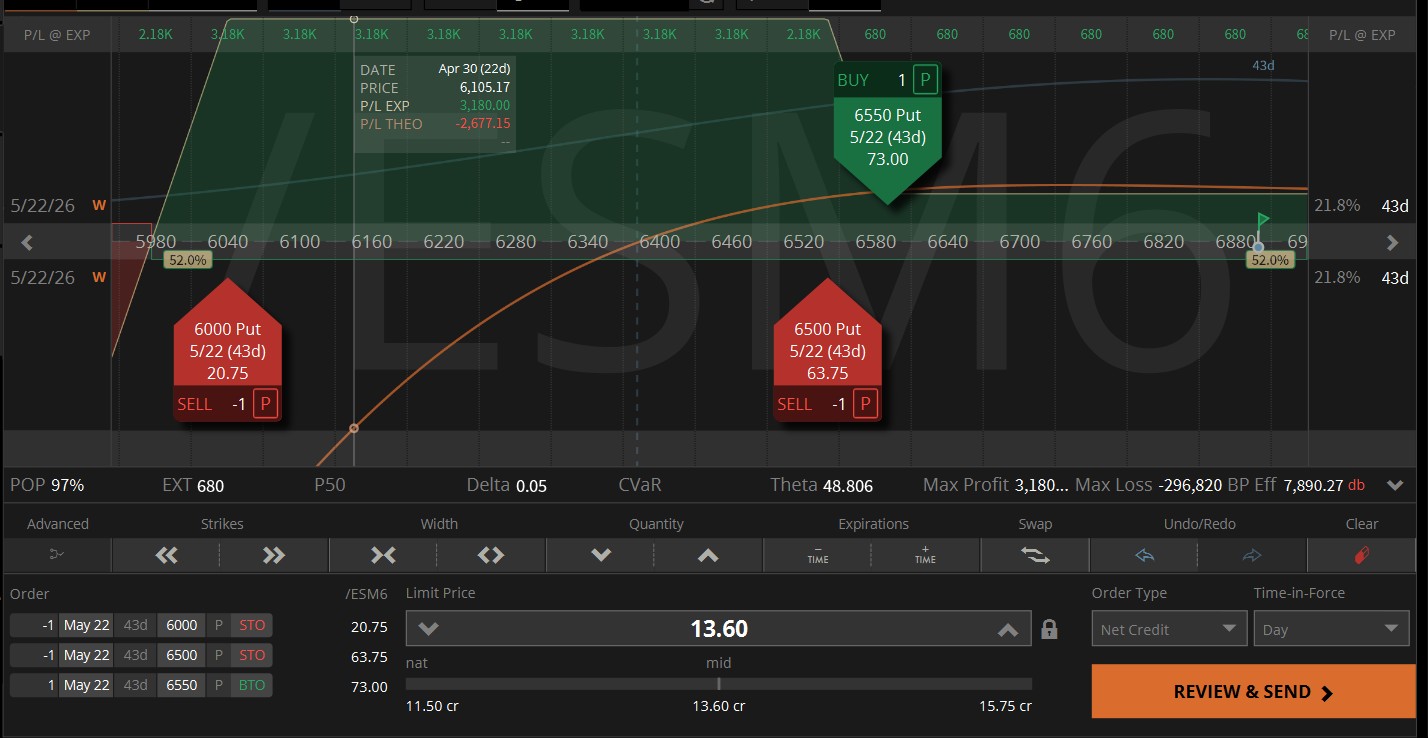
A Systematic Framework for Volatility Harvesting & Risk Governance
Most income strategies are structurally fragile. They thrive in a state of “calm weather” but are mathematically incapable of surviving a systemic storm. The 1-1-1 Strategy is a deliberate departure from this fragility.
It is a high-probability, “campaign-style” volatility system designed to harvest the Volatility Risk Premium (VRP) while maintaining a structural “Bear Trap.” By utilizing a specific configuration of long and short puts, this framework creates a convexity hedge that protects against moderate corrections while financing the trade through deep out-of-the-money (OTM) risk.
Strategy Lineage & Credits
This framework is a synthesis of institutional volatility theory and real-world mechanical refinement. It draws from:
- The King Ratio: Foundational pricing and ratio mechanics pioneered by Tom King.
- Convex Hedging: The structural “Bear Trap” architecture developed by Bobby Gaines (Sweet Bobby) and MRTOPTICK.
- Systematic Management: Mechanical trade protocols popularized by Tony Rihan (Uncle Tony) and Zoheb Noormohamed.
- Tactical Entry: The end-of-day execution logic refined by Austin Bouley.
This playbook is further grounded in historical quantitative research by Collins (2006) and Rostan (2019), ensuring the system is optimized for nonlinear Greek management (Vanna/Vomma).
1. Strategy Structure: The Setup
The strategy is deployed in highly liquid futures: /ES, /MES, /CL, and /GC.
| Component | Target Action | Strike Selection & Pricing |
| Income Leg | Sell 1 Put | 7–10 Delta |
| Hedge Leg (Long) | Buy 1 Put | 25–30 Delta |
| Hedge Leg (Short) | Sell 1 Put | Asset Scaling: 50 pts below Long (/ES) or ~5% of asset price (/CL, /GC) |
- Expiration (DTE): 60–75 days.
- The “3:30 Rule”: All entries must be executed in the final 30–60 minutes of RTH to capture the day’s true settlement sentiment.
2. Entry Logic Hierarchy
To ensure the trade is placed in a high-probability environment, we categorize filters by priority:
A. Core Conditions (Structural Requirements)
- Trend Filter: Price > 200-day SMA AND 10-week EMA > 20-week EMA.
- Regime Filter: Market environment should ideally show VIX < 25.
- Pricing Gate: IV Rank > 25% (ensuring the VRP is worth harvesting).
B. Timing Signals (The Tactical Edge – Optional)
- Red Day Preference: Entry is prioritized after a 1.5%–2% down day.
- Mean Reversion: Entry is prioritized when 14-period RSI is < 40.
3. Capital Allocation & Portfolio Heat
- Single Campaign Risk: Max 2% of total portfolio value.
- Maximum Portfolio Heat: Total combined risk across all campaigns ≤ 6%–8%.
- Cash Buffer: 60–70% in liquid cash/T-bills (SGOV) held to prevent forced liquidation during SPAN margin expansion.
- Exposure Note: Risk is defined as net directional delta exposure, not just contract count.
4. Pre-Trade Risk Gate: The Stress Test
Before every entry, perform a Vanna & Vomma Stress Test:
- Simulate a +20 or +30 VIX spike.
- Pass/Fail: If a single position contributes >10% projected drawdown to the total portfolio, the trade is FAILED.
- Protocol: Reduce position size or defer the trade until volatility normalizes.
5. The Exit Priority Hierarchy
Rule of Linear Evaluation: Rules are evaluated from top to bottom. The first triggered rule takes full precedence.
- Volatility Shock Override: If VIX increases >40% in 1–3 days, close/reduce naked exposure immediately. No new entries for 2 trading sessions.
- Emergency Roll/Exit: If delta increases sharply (e.g., >10 delta increase within a short period) and a credit roll is unavailable or liquidity is insufficient, exit the full position.
- Hard Time Exit (21 DTE Rule): Close the entire position at 21 DTE regardless of P/L.
- Risk Management (30 Delta Rule): Adjust or roll if the short put reaches 30 delta.
- Primary Profit Exit: Close at 70–80% profit OR if Delta < 2.
- Technical Exit: Optional early exit if price breaks above the Upper Bollinger Band (200-period).
6. Risk Control & Rolling System
- Primary Action: Execute a “Down and Out” roll. Move strike lower (10–15 delta) and extend time (30+ days).
- Net Credit Mandate: Rolling is strictly conditional on receiving a net credit. If unavailable, reduce risk/size instead.
7. Hedge Architecture: Legacy Convexity
After closing the income leg, the Put Debit Spread (PDS) remains as a Legacy Convexity Hedge. Exit the leftover PDS when:
- Hedge loses >80% of its value.
- Time decay becomes dominant (< 10 DTE).
- Hedge is inactive (delta exposure becomes negligible relative to spot price).
8. Strategy Philosophy
- Volatility is the source of return.
- Risk is nonlinear: Greeks (Vanna/Vomma) move faster than the underlying price.
- Liquidity is a position: Cash is the armor that survives the “Liquidity Trap.”
🛠 Deployment Checklist
- [ ] Structural: Price > 200 SMA AND VIX < 25 AND IVR > 25%?
- [ ] Tactical: Red day OR RSI < 40?
- [ ] Stress Test: Pass < 10% projected drawdown on VIX +20 spike?
- [ ] Allocation: Single risk < 2% and Portfolio Heat < 8%?
- [ ] Timing: Is it between 3:30 PM and 4:00 PM EST?
📚 Bibliography
- Bobby Gaines, Tom King, and MRTOPTICK, “1-1-1 and 1-1-2 Systematic Mechanics and Notional Sizing Protocols,” 2024.
- Tom King, “The OG 1-1-1: Pricing Ratios and Bear Trap Management,” Income Navigator Masterclass, 2023.
- Zoheb Noormohamed, “Inside the 1-1-1 Options Strategy: Rules, Mechanics, and Results,” Theta Profits, 2025.
- Zoheb Noormohamed, “Tactical Filters: IV Rank and the 20% Distance Rule,” 2024.
- Collins, “Beating the Financial Futures Markets: Combining Small Biases into Money-Making Strategies,” 2006.
- Bobby Gaines, “Consistently is Attainable: Scaling the Sweet Bobby Hedge,” 2024.
- Pierre Rostan et al., “Options trading strategy based on ARIMA forecasting: A Historical Look at Ratio Spreads,” 2019.
- Austin Bouley, “Why An End of Day Entry Is Best For Credit Spreads,” 2023.
- Todorov & Vilkov, “The 180% VIX Spike: Bid-Ask Spread Expansion and the Liquidity Trap,” BIS Bulletin, 2024.
- Reddit r/thetagang, “SPAN Margin and Risk Post-Mortem: Lessons from August 5, 2024.”
🔗 Works Cited & Digital Resources
- Strategy Breakdown: Inside the 1-1-1 Options Strategy
- Foundational Mechanics: How to Trade the 111 Strategy – Tom King
- Performance Analysis: This Options Strategy Can Deliver 60% Returns
- Futures Implementation: 111 Put Option Trade in /MES Futures
- Community Wisdom: Consistently is Attainable (r/thetagang)
- Risk Discussion: Short Strangles on Futures (r/options)
- Code/Notes: Private Geldanlage Repository (GitHub)