
🏰 Building a Fortress in a 2% Storm
The tape is getting wild. With the /VX screaming at 25.65 and the /ES taking a sharp 2% intraday haircut, most traders are heading for the exits or tightening their stops. The market is currently bracing for a staggering +/- 240.70 move for the March 20th cycle.
While the herd sees chaos, I see an opportunity. I’m leaning into the fear and using it to build a fortress.
🛠️ The Strategy: The “Step-Up” Bullish Skew
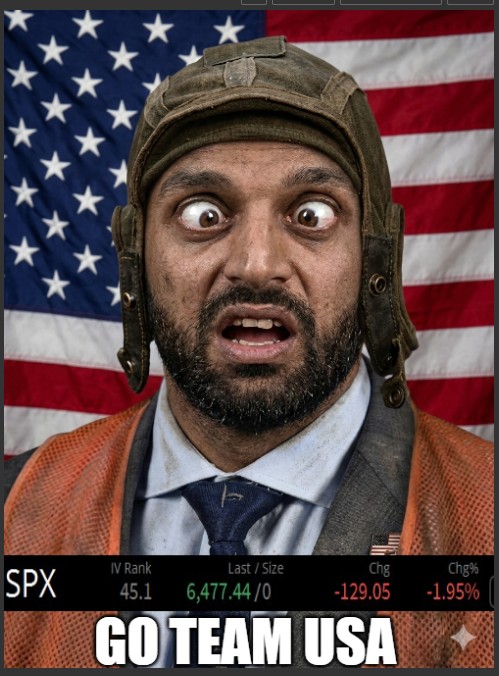
I’ve put on a custom /ES position that flips the traditional Iron Condor on its head. Instead of being neutral, I’ve engineered this so that I’m actually rooting for a rally while staying protected from a total meltdown.
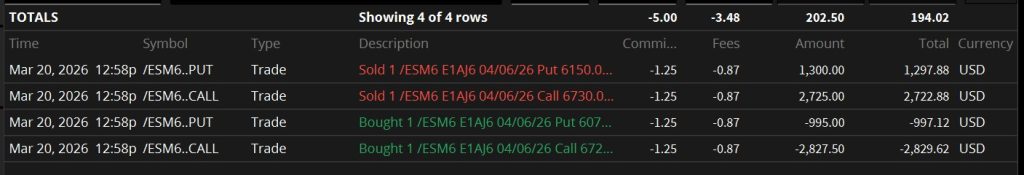
| Leg Type | Strikes | Width | Logic |
| Put Wing | 6150 / 6070 | 80 Pts | Selling fear 500 points below the current price. |
| Call Wing | 6725 / 6730 | 5 Pts | A “Step-Up” booster for an upside breakout |
🛠️ The Blueprint
I’m using an asymmetric setup that combines a massive safety net on the bottom with a profit booster on the top.
| Leg Type | Strikes | Width | Strategy |
| Put Wing | 6150 / 6070 | 80 Pts | Credit Spread (Selling Fear) |
| Call Wing | 6725 / 6730 | 5 Pts | Debit Spread (Buying the Breakout) |
💰 The Profit Scenarios
Because this is a “broken wing” style setup, there are two ways to walk away with a paycheck:
- The “Sweet Spot” (Inside the Box): If the market stays between 6150 and 6725, I collect a base profit of $202.50.
- The “Moonshot” (Upside Breakout): If we blast through 6730, the trade “steps up” and I walk away with $452.50.
⚠️ The Reality of Risk (Max Loss)
We have to talk about the elephant in the room. This trade has a Max Loss of -$3,797.50.
- The “Why”: That 80-point wide put spread is where the risk lives. If the S&P 500 drops over 7.3% and settles below 6070, that’s where the floor falls out.
- The Probability: My short put at 6150 is nearly 500 points away from the current price. While the risk number is large, the Probability of Profit (POP) is sitting at a healthy 90%. I’m betting on the stats, not the outliers.
🧠 The IVX “Edge”
My specific trade legs are showing an IVX of 25.4.
Why does that matter? It sits right in the pocket of the broader market /VX (25.65). This is the secret sauce. By selling options when IV is this high, I am capturing a “volatility premium.” I’m essentially selling insurance when it’s priced at its most expensive. When fear peaks, premium sellers get paid the most.
📊 The Greeks Dashboard
This is the “engine room” that tells me how the position is breathing:
- Theta (13.97): I’m decaying at nearly $14.00 per day. The clock is my best friend. Every sunset is money in the pocket.
- Delta (0.04): I have a tiny bullish lean. I don’t need a rally to win, but if the market recovers from today’s 2% dump, I hit that $452.50 plateau even faster.
- Vega (Short Vol): I am “Short Vol.” If the market calms down and the VIX drops, the value of this spread melts, allowing me to close early for a win.
🛡️ Final Verdict
This is a high-probability income play with an “upside bonus” built into the ceiling. I’m trading the risk of a black-swan crash for a very high chance of collecting rent while the rest of the market is panicking.f collecting rent in a volatile market.
Leave a Reply