
The S&P 500 is currently sitting at 6575, but the real story today isn’t the price—it’s the cost of protection. With the VIX hitting 24.80, I’ve officially shifted into a high-volatility regime.
If you’ve been following my recent trades, you’ll notice a distinct change in my playbook today. Over the last few months, I’ve been leaning heavily into Calendar Spreads. When volatility is low (VIX in the 12-15 range), I like Calendars because they allow me to “buy time” and benefit if IV eventually ticks up. But once the VIX crosses that 20-22 threshold, the math changes for me.
In this environment, I find Calendars risky because of “IV Crush”—if the market stabilizes and volatility drops, those long-vega positions will bleed out. Instead, I’m moving toward Short-Vega structures like Iron Condors and Broken Wing Butterflies (BWBs). I want to be a seller of this expensive fear, not a buyer.
Here’s how I’m positioning my capital for the next few weeks.
Trade 1: SPX May 15th Iron Condor
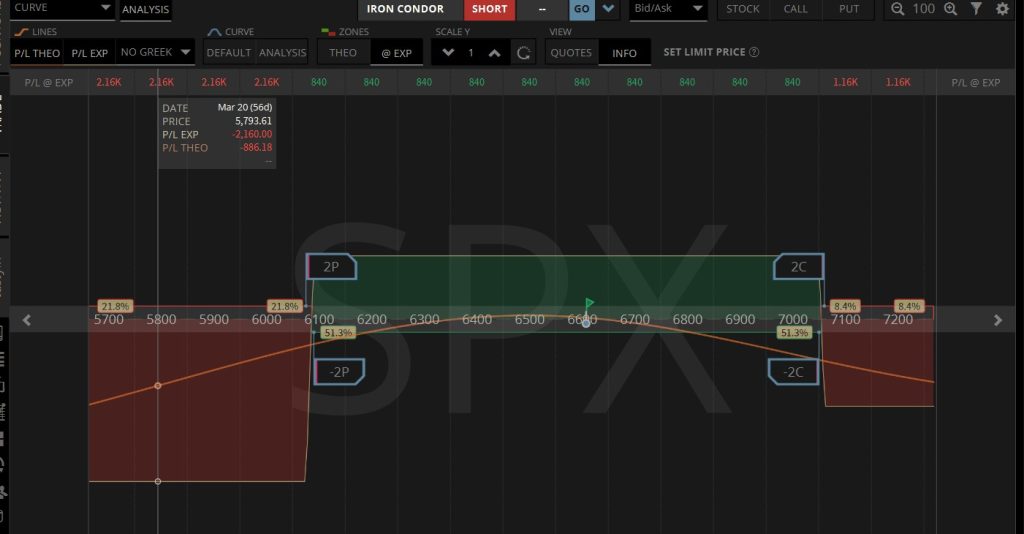
The Setup: I sold the 6090P/6075P spread and the 7050C/7060C spread.
- Net Credit Collected: $420
- Max Risk: $1,080
- Return on Risk: 38.8%
The Strategy: This is my primary “income” trade. By selling a 15-point wide put spread and a 10-point wide call spread, I’m harvesting these high premiums. My breakevens are roughly 6085 on the bottom and 7055 on the top. This gives me nearly 500 points of cushion in either direction. At a VIX of nearly 25, I’m betting that the “implied” move the market is pricing in is actually larger than the “actual” move we’ll get.
Trade 2: SPX April 30th Put Broken Wing Butterfly
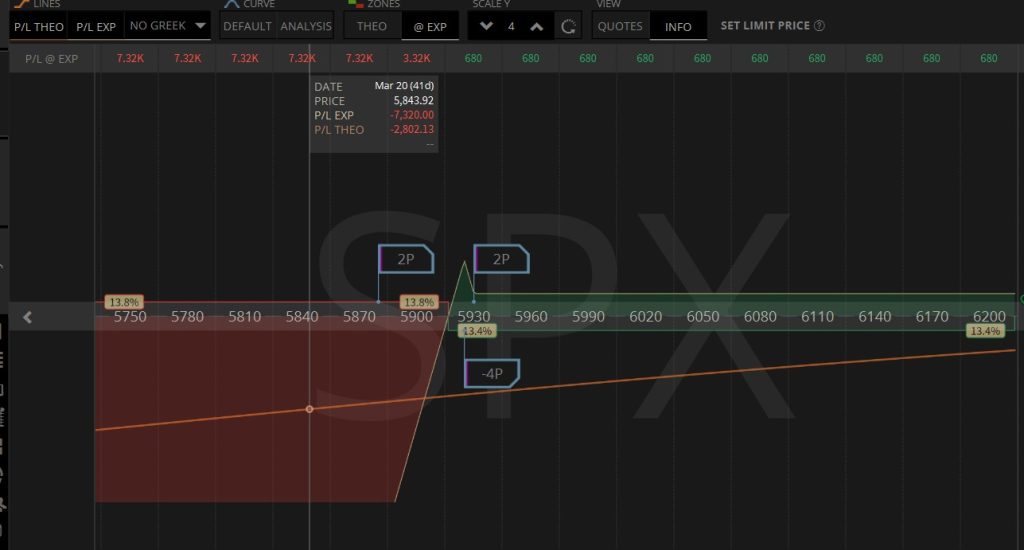
The Setup: 2x Long 5930P / 4x Short 5925P / 2x Long 5880P.
This is a tactical “set and forget” trade I’ve placed way out of the money.
- Net Credit Collected: $680
- Max Profit: $1,680 (if SPX pins at 5925)
- Max Risk: $7,320 (if SPX crashes through 5880)
- Upside Risk: $0.00
The Strategy: The beauty of this BWB is the net credit. Because I collected $680 to put this on, I have absolutely no risk if the market continues to rally or stays right here at 6575. If the S&P 500 never touches 5930, I simply walk away with the $680.
However, if I see a controlled “flush” down toward the 5900-6000 range, this trade enters the “profit tent.” It’s a way for me to get paid for holding a lottery ticket that pays off in a moderate downside scenario, without the theta decay pain of a standard long put.
Trade 3: SPX April 6th (18-Day) Custom Iron Condor
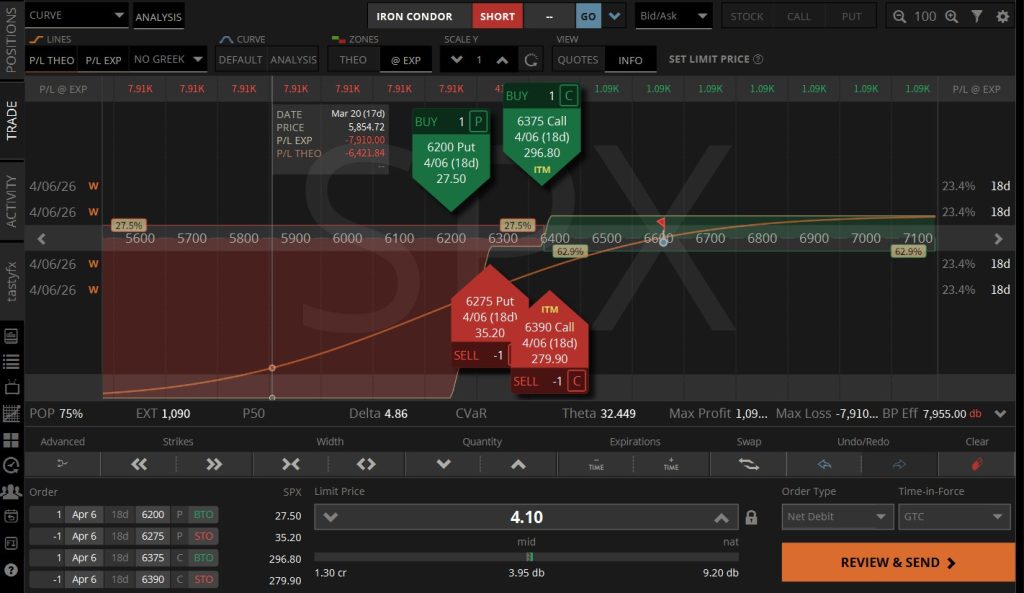
The Setup: 1x Long 6200P / 1x Short 6275P / 1x Short 6390C / 1x Long 6375C.
Yes, you read that right. This is an Inverted or “Custom” Iron Condor.
- Net Debit Paid: $410
- Max Profit: $1,090 (if SPX stays above 6390 or below 6200)
- Max Risk: $7,910 (if SPX is caught between 6275 and 6390 at expiration)
- Break-Even Zone (The Danger Zone): 6211 to 6379.
The Strategy (Contrarian Play): Unlike my other trades, I paid a debit for this one. This is my “chaos catcher.”
Look at the P/L chart above (Image 3). If SPX stays right here at 6575, I make full profit. This trade only loses money if the market slides back down precisely into the 6275-6390 range by April 6th. That 6275-6390 range is where the market was trading just a few weeks ago before this recent breakout. I’m basically betting that we either keep marching higher OR we crash violently past that zone and re-test the low 6000s. I find the scenario where we slide back down only 5-10% and “pin” there for three weeks to be the least likely outcome.
My Bottom Line
When Volatility is low, I buy it (Calendars). When Volatility is high, I sell it (ICs and BWBs).
By pivoting today, I’ve collected net credits on my long-dated income positions, while paying a small debit to capture potential high-velocity moves in the short term. I’m comfortable with the risk levels here because the BWB provides a “free” hedge against a moderate slide, the long Iron Condor harvests the daily decay, and the Custom Iron Condor protects against extreme volatility (including extreme upside).
I’m staying disciplined—high VIX means high opportunity, but only if I manage my size.
Current Portfolio Stats:
- SPX: 6575
- VIX: 24.80
- My Stance: Diversified Short Volatility / Convexity Long.
Leave a Reply