1. 📌 Strategy Overview
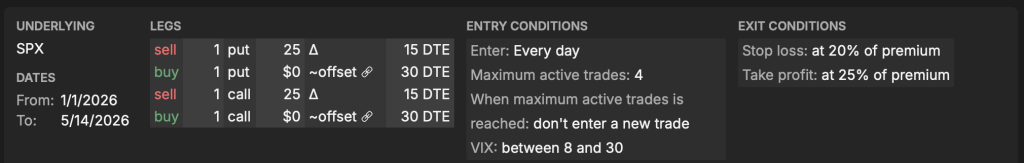
A short-duration, structured double calendar strategy designed to profit from volatility expansion and time decay differential while limiting directional risk through defined entry filters and mechanical exits. This system utilizes a 15 DTE short option paired with a 30 DTE long option to create a net long vega position. It is a mechanical system requiring no discretionary adjustments.
2. 🌍 Market Selection
- Eligible Underlyings: SPX, ES, and MES (High liquidity and tight bid/ask spreads).
- Volatility Filter (Hard Rule): VIX must be between 8 and 30 at entry.
- Rationale: The strategy performs best in lower-to-moderate volatility environments where IV has room to expand.
3. 🧩 Trade Structure (One Unit)
The trade consists of two separate calendar spreads entered simultaneously for a net debit.
- Put Calendar: Sell 1 x ~30Δ Put (15 DTE) / Buy 1 x Put (30 DTE) at the same strike.
- Call Calendar: Sell 1 x ~30Δ Call (15 DTE) / Buy 1 x Call (30 DTE) at the same strike.
- Alternative Loadouts: While 30Δ is the backtested “Standard Issue,” users may adapt to market speed:
- The Sprinter (40Δ): Used in low VIX (<12) to capture decay in quiet markets.
- The Defender (25Δ): Used in elevated VIX (20–26) to provide more geographical room.
4. 📅 Entry Rules & The “Pre-Flight” Scan
- Timing: Preference for Wednesdays. Wait 15 minutes after the open to avoid wide spreads.
- The IV Ratio (Horizontal Skew): Calculate Ratio = IV_Short (15 DTE) / IV_Long (30 DTE).
- > 0.95: Green Light (Neutral/Backwardation).
- < 0.90: NO TRADE (The Contango Trap).
- The Skew Scan (Vertical Skew): Puts must be significantly pricier than Calls. If the Call side is more expensive, No Trade.
- The EM Anchor (Safety Check): Calculate the 1.0x Expected Move as (Price x IV) / 10. Ensure your short strikes are at or beyond 1.2x this EM to maintain the 82.5% win rate.
| IV Ratio (IV15/IV30) | Status | Action / Logic |
| < 0.90 | Contango Trap | NO TRADE. Buying expensive, selling cheap. No Theta edge. |
| 0.95 – 1.05 | The Sweet Spot | GREEN LIGHT. Ideal balance of safety and decay. |
| > 1.05 | Panic Harvest | GREEN LIGHT (Reduce Size). High profit potential, but high risk of hitting Hard Stops due to volatility. |
5. ⏹ Exit Rules (The Harvest Protocol)
A trade must be closed when ANY of the following occur:
- ✅ The 10% “Wake Up” Call (Take Profit): At +10%, you must choose to Bank or Run.
- Bank it if: Price is near a short strike, Net Delta is > 15, or you are < 4 days to expiry.
- Run it if: Price is centered in the “Valley” and you have 5+ days to expiry. Move the mental stop to +5% and exit at the +25% hard ceiling.
- 🛑 Stop Loss: Close immediately at -25% of total debit paid. Beyond this, recovery probability drops to ~12% and losses accelerate.
- ⏳ 48-Hour Kill Switch (Time Exit): Mandatory exit 48 hours (2 days) before the 15-day shorts expire, regardless of P/L.
6. 💰 Risk Profile
- Defined Risk: Maximum loss is limited to the premium paid.
- Profit Drivers: Volatility expansion (Long Vega), time decay differential, and favorable term-structure shifts.
- Primary Edge: The trade relies on volatility expansion, not just pure theta decay.
7. 📊 Structural Behavior & Geometry
- The Valley: The area between strikes where Delta is low and Theta is the driver.
- Standard Deviation Coverage: A 30Δ structure typically covers 1.2x the 15-day EM.
- The Vol Shock Absorber: Downside moves (VIX Up) “inflate” the Put tent, allowing survival up to 1.5 SD. Upside moves (VIX Down) “shrink” the Call tent, often hitting stops at 0.8 to 1.0 SD.
8. 🛑 Known Failure Modes
- Contango Trap: Entering when back-month IV is overpriced leads to an “Instant Stop”.
- Skew Flattening: If Puts lose “fear” faster than Calls, the Put-side calendar loses value even if price is stagnant.
- The “Slip” Effect: In the final 48 hours, a tiny price move can cause a 30% P/L swing due to extreme Gamma.
9. 🧠 Strategy Philosophy
- Volatility is the Margin of Safety: We sell “juiced” front-month vol and buy “cheap” back-month vol to create a “Vol Shield”.
- Harvesting, Not Gambling: We focus on preserving the 80% win rate by exiting before the “Mega Gamma” zone.
10. 🔒 Rule Integrity
No modification of the 15/30 structure, VIX filters, or exit thresholds without independent testing. Adhering to the IV Ratio and Kill Switch is non-negotiable for capital protection.
11. 📈 Greek Exposure Breakdown (The Physics of the Flip)
| Greek | At Entry | Mid-Cycle (Day 5-9) | Near 15 DTE Expiry |
|---|---|---|---|
| Delta | Near neutral | Builds if trending | Accelerates rapidly |
| Vega | Net long (Primary Edge) | Strong driver | Less dominant |
| Theta | Small positive | Increasing benefit | Strong if stable |
| Gamma | Low | Rising (Active) | Explosive (Danger) |
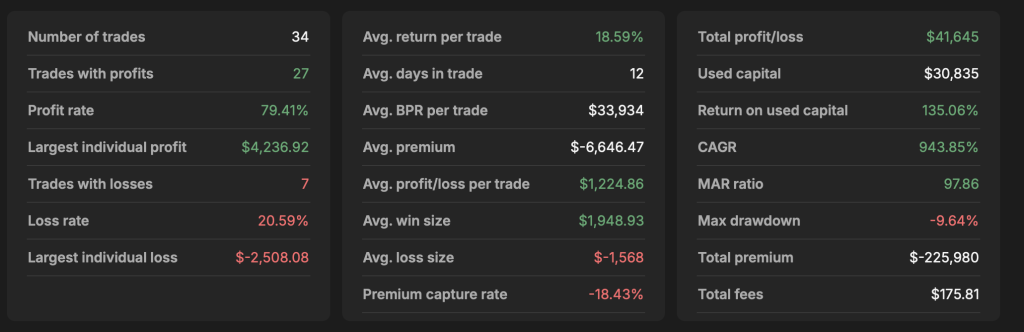
12. 📊 Backtested Performance Snapshot (30Δ Basis)
| Metric | Value | Metric | Value |
|---|---|---|---|
| Win Rate | 82.5% | Avg Return/Trade | 6.39% |
| Avg Days in Trade | 6 | Max Drawdown | -36.46% |
| MAR Ratio | 3.25 | Return on Capital | 118.36% |
| Number of Trades | 40 | Total Profit/Loss | $15,807 |
Performance reflects mechanical exits at 10% TP, 25% SL, and 13-day (or 48-hour) time stop.
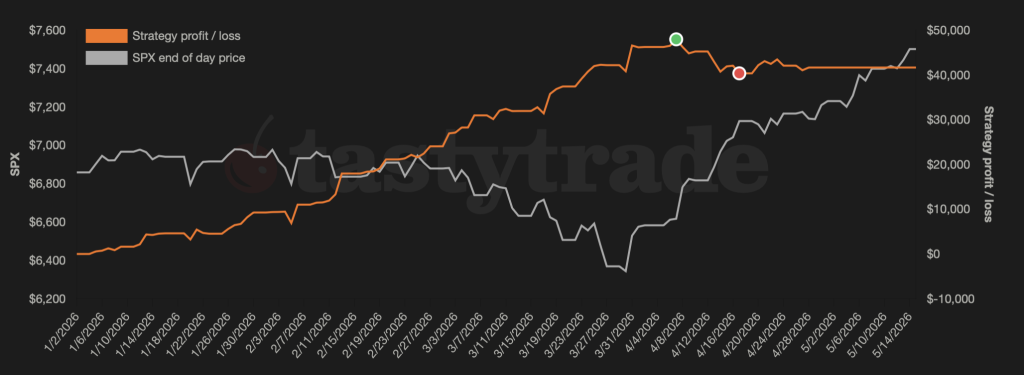
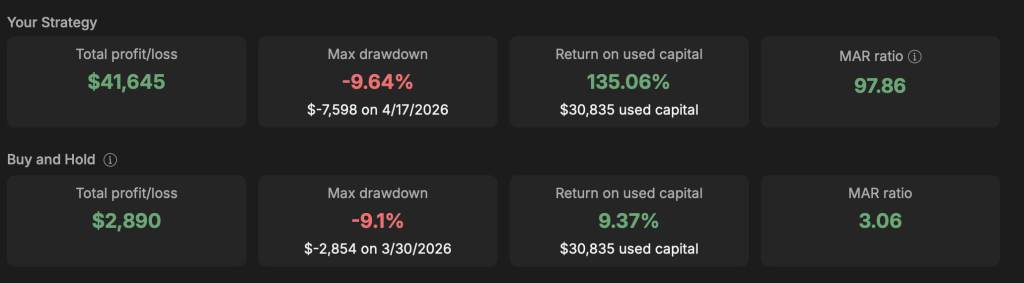
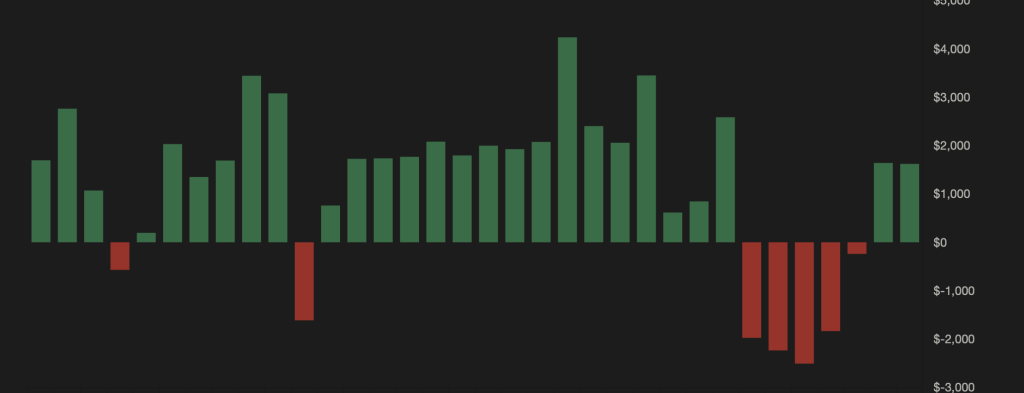
TastyTrade Backtesting Example