
The market is throwing a tantrum, and I’m here to collect the “fear tax.” With the S&P 500 futures (/ES) trading around 6572 and the VIX futures (/VX) hovering at a spicy 25.53, implied volatility is high enough to make an Iron Condor look like a statistical powerhouse.
When volatility is this high, the market often overestimates how far it will actually move. I’m betting that the /ES stays within a specific range over the next 21 days, allowing me to pocket the premium as these options decay.
The Strategy: The April 16 Iron Condor
I’ve structured this trade to give the market massive room to breathe. By using these specific strikes, I’ve built a “profit tent” that is incredibly resilient.
The Position Details:
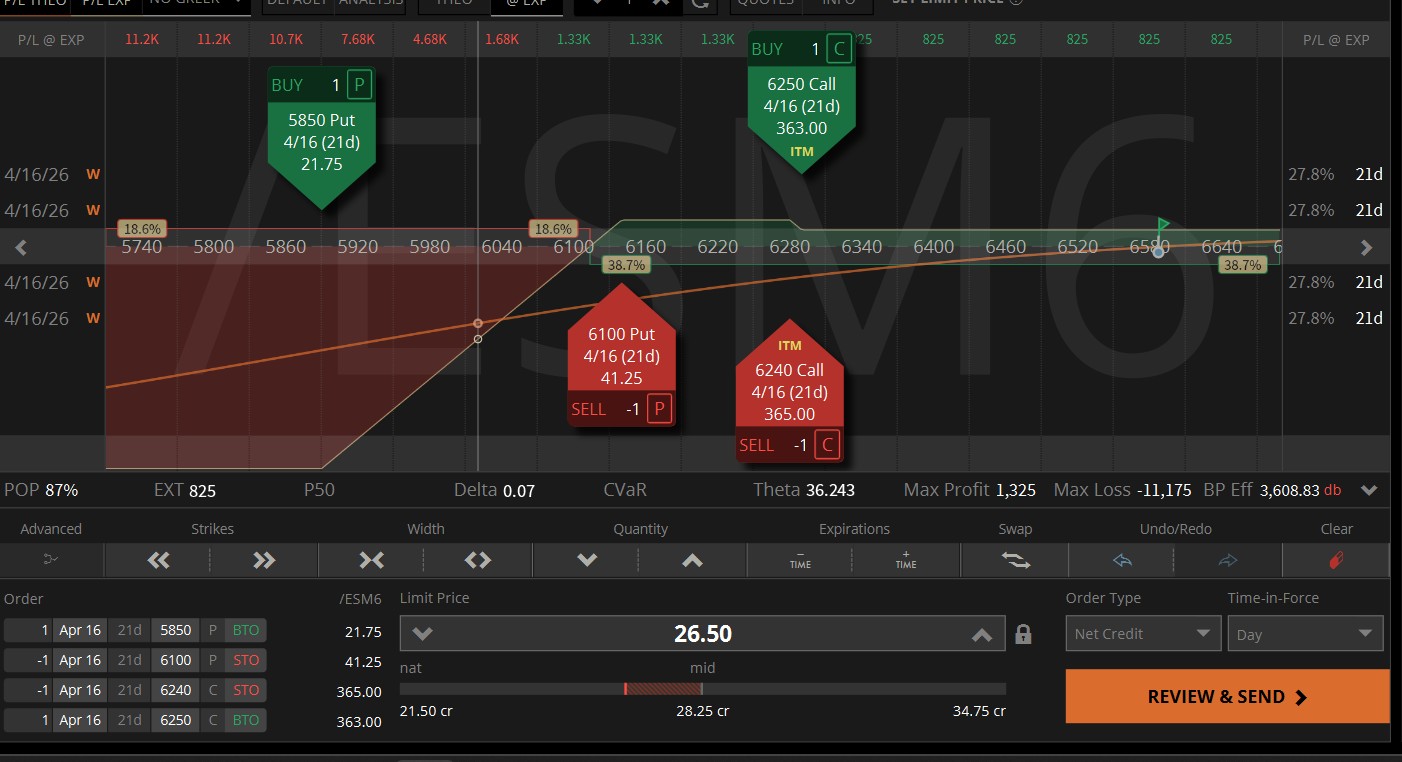
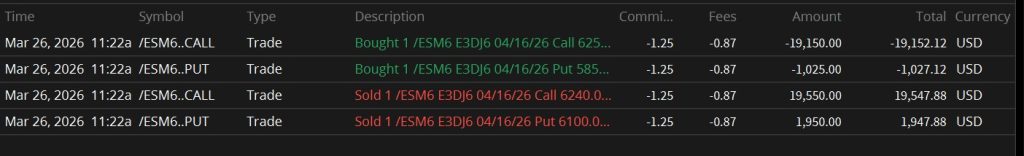
- The Call Side: Sold 1 6240 Call / Bought 1 6250 Call
- The Put Side: Sold 1 6100 Put / Bought 1 5850 Put
- Net Credit Received: $26.50 (mid-price)
The “Statistical Edge”: 87% Probability of Profit
This is the hero number of the trade. According to the analysis tab, this setup enters with a POP of 87%.
In a market where the /VX is sitting at 25.53, being able to structure a trade with nearly a 90% statistical chance of success is a massive advantage. It shows just how much “room to move” the market is giving us. Even if the /ES wanders, as long as it stays within our broad profit zone by April 16, we hit the mark.
The Greeks: The Engine Under the Hood
Pulling directly from the live trade desk, here is how the position is built:
| Greek | Value | Impact on the Trade |
| Delta | 0.07 | We are almost perfectly delta-neutral; price movement is a non-factor right now. |
| Theta | 36.24 | The Heartbeat: We are collecting $36.24 per day in time decay. |
| Max Profit | $1,325 | The total potential gain for this 1-lot. |
| Buying Power | $3,608.83 | The collateral required to hold the position. |
Why This Works
With the underlying at 6572, I’ve positioned this condor with a very interesting look. By selling the 6240 Call (which is In-The-Money) and the 6100 Put, I’ve created a massive profit zone. Because the /VX is so high, the “extrinsic” value in these options is bloated. I am essentially getting paid a high premium to wait for the market to settle down.
Risk Management & Exit Plan
I’m not looking to hold this until the final bell on April 16. Here is my blueprint:
- Profit Target: I’ll look to close this out for 50% of the maximum profit (around $660).
- Stop Loss: If /ES threatens our 6100 floor or breaks significantly above current levels, I’ll be looking to adjust or exit to preserve capital.
- The “Vol Crush”: If we get a 2-3 day rally and the /VX drops toward 20, the high negative Vega in this trade will accelerate our gains, potentially hitting our target much sooner.
Final Thoughts
With an 87% POP and a Theta of 36, the math is heavily in our favor. We aren’t guessing which way the market goes; we are simply betting that it won’t move more than the high-volatility pricing suggests.