
🚦 Market Regime Filter
| Metric | Value | Status |
| VIX | 17.93 | 🟢 Optimal (8-30) |
| Term Structure | Contango | 🟢 Confirm Back IV >= Front IV |
| Regime Check | Binary Risk | ⚠️ NVIDIA Earnings / Post-Tariff Vol |
🛠️ The Setup Table & Range
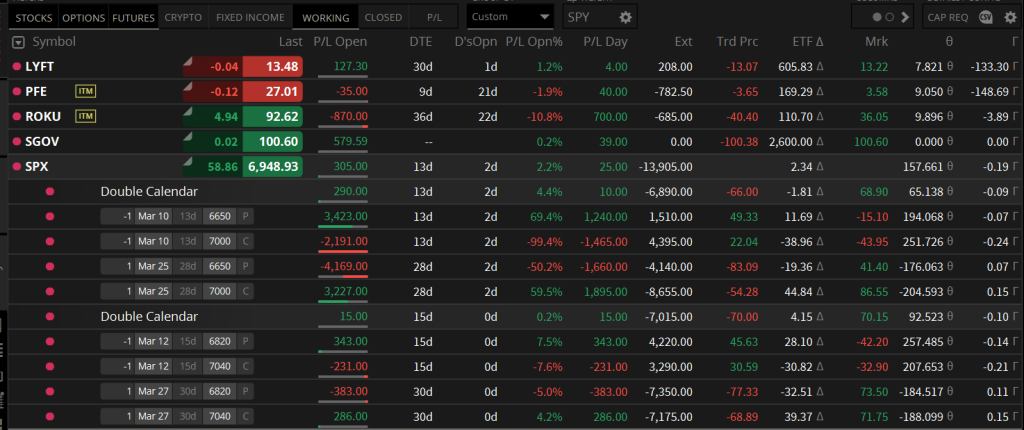
| Leg | Expiration | Strike | Delta |
| Put Calendar | MAR 12 / MAR 27 | 6675 | ~30Δ |
| Call Calendar | MAR 12 / MAR 27 | 7100 | ~30Δ |
📍 Estimated Profit Zone: > Lower Breakeven: $6,574.88 | Upper Breakeven: $7,206.50 Range: Approx. ±1.5% beyond the strikes at front-month expiration.
📈 Execution & Risk Metrics
Date Opened: February 25, 2026
Total Debit: $24.50 Calculation: Leg 1 + Leg 2 – Leg 3 – Leg 4 = $24.50 10% Evaluation: $26.95
🛑 Hard Stop (-25%): $18.38 (Exit immediately)
Target Exit Date: March 10, 2026
💰 Profit Potential Ladder (Per Unit)
| Return | Exit Price | Dollar Gain |
| +10% | $26.95 | +$245.00 |
| +20% | $29.40 | +$490.00 |
| +30% | $31.85 | +$735.00 |
| +40% | $34.30 | +$980.00 |
🧠 Strategic Extrapolations (The Deep Dive)
🎯 Expected Move Alignment: The March 12 expiration carries a ±3.1% expected move ($211.69). Our strikes at 6675 and 7100 sit just outside the 1-standard deviation move, allowing the index to breathe while we harvest decay.
⚡ Gamma Risk: As we approach the March 12 front-month expiration, Delta will begin to accelerate rapidly near the 6675 and 7100 strikes. If price pins near these levels, the “gamma flip” can create explosive P/L gains, but requires strict adherence to the exit date to avoid expiration pin risk.
🌫️ Volatility Dispersion: While the VIX has cooled to 17.93, the “Nvidia Shadow” remains. With NVDA earnings hitting tonight, the dispersion between index volatility and constituent volatility is at a local peak. This trade benefits if index vol stays anchored while individual names churn.
🧱 The “Call Wall” Analysis: Significant open interest is clustering at the 7100 level. This acts as a natural ceiling for the current campaign, aligning perfectly with our upper strike. We expect the index to struggle to sustain a move above this magnet.
⏳ Theta/Vega Ratio: By selling the March 12 (15 DTE) and buying the March 27 (30 DTE), we are net long Vega. This protects the position against a sudden market-wide vol spike, while the front-month Theta decays at an accelerating rate compared to the back-month.
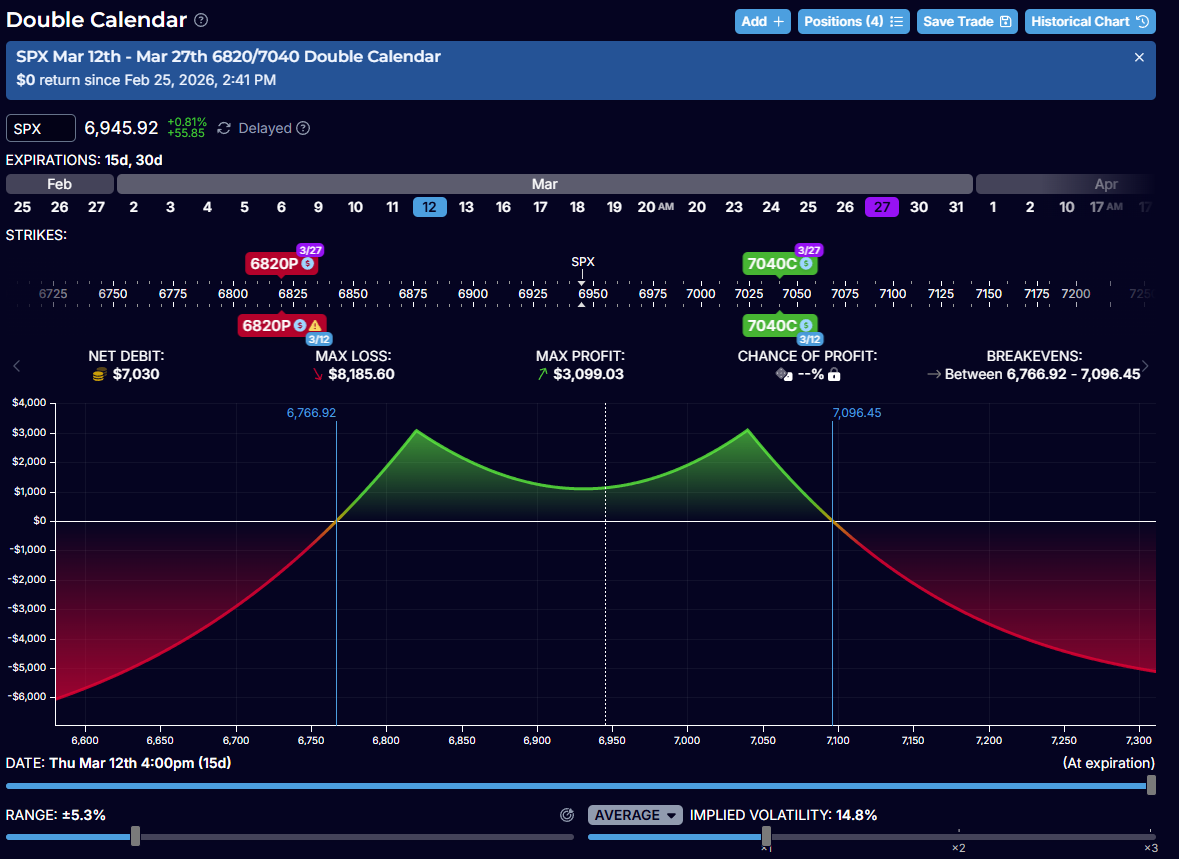
📉 Visualizing the Trade Mechanics
- The Valley vs. The Peaks: The trade opens in the “valley”—a flat P/L zone near current price. As the index moves toward the 6675 or 7100 strikes, the position “climbs” the profit peaks where the tent is tallest.
- The Theta Burn: Every 24 hours that the SPX remains between our strikes, the front-month options lose more value than the back-month longs, effectively “inflating” our profit tent daily.
🛡️ Strategy Integrity
- Thesis: Harvesting front-month theta vs. back-month volatility expansion.
- Invalidation: Price breach of breakevens or sudden front-month vol spike.
- NO ADJUSTMENTS: No rolling, no scaling, no averaging down.
- Execution: Mid-price, walk $0.05 every 30s. GTC stop set immediately.
“Process > Outcome. Stay disciplined.”
Leave a Reply