
In a market defined by a VIX hovering near 25 and geopolitical “known unknowns,” passive investing is a gamble. I prefer to be the house.
Last night, I initiated a Jade Lizard on the S&P 500 (/ES) for the April 30th expiration. While many retail traders view this as a “neutral” play, I view it as a surgical strike on Overstated Volatility.
The Structure: Engineering the “No-Upside-Risk” Wall
A Jade Lizard is more than just a collection of Greeks; it’s a math problem. Here’s the blueprint:
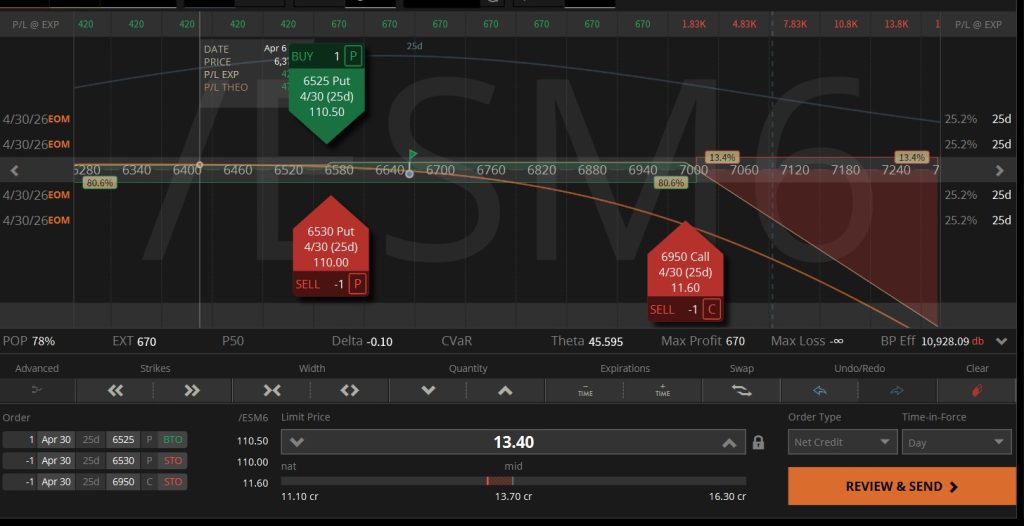
- The Put Side: Sold the 6530/6525 Credit Spread (5-point width).
- The Call Side: Sold the 6950 Naked Call.
- The Total Credit: $13.40 ($670 per contract).
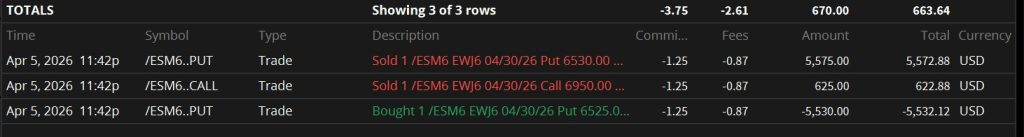
The Quantitative Edge: Notice the width of the put spread is $5.00 ($250 risk). Because I collected $13.40 in total credit, I have effectively eliminated upside risk from the spread itself. My credit is greater than the spread width. My only “real” risk is a vertical moonshot past 6963.40 (Call Strike + Total Credit).
The Macro Narrative: Trading in a “Stagflation Lite” Era
I didn’t pick these strikes out of a hat. I looked at the market’s current speed limit:
| Metric | Value | Strategist’s Note |
| Asset | /ES (S&P 500) | Currently trading near 6603.75. |
| /VX (Futures Vol) | 24.45 | Fear is elevated; premiums are fat. |
| IVx (Implied Vol) | 25.2 | Volatility is “on sale” for sellers. |
| Expected Move | ± 294 pts | The statistical “lane” for the next 25 days. |
The Backdrop: With Brent Crude surging past $111/barrel due to Strait of Hormuz tensions and U.S. manufacturing PMI showing surprise resilience, the market is trapped in a tug-of-war. This trade thrives on that indecision. By placing my short call at 6950, I am positioned well outside the upper bound of the expected move ($6897$).
The “Greek Edge”: Making Time My Employee
Every morning I wake up, this trade “pays” me through the erosion of fear.
- Theta (+45.59): I am harvesting the “Fear Tax.” As long as the S&P 500 doesn’t teleport 5% in either direction, time decay erodes the value of the options I sold.
- Delta (-0.10): I have a slight bearish tilt. If the market drifts lower or stays flat, I win faster.
- Vega: I am betting on an IV Crush. If geopolitical tensions de-escalate and VIX drops back to 20, the price of these options will collapse, allowing an early exit.
The Safety Moat
My Downside Breakeven is 6516.60. That represents a significant cushion below the current price. We would need to see a break of the critical 6500 psychological support before this trade even smells a loss.
Management Plan: The Strategic Pivot
Trading without a plan is just gambling with extra steps. Here is the “If/Then” logic:
1. The 50% Rule (Profit Target)
I am not looking for a home run. When the trade shows a profit of $335 (50% of credit), I’m out. The last 50% of profit takes 90% of the stress; I’d rather recycle the capital into a new setup.
2. The Iron Condor Conversion (The Fire Extinguisher)
If /ES catches a bid and pierces 6900, the naked 6950 call becomes a delta-headache. I won’t wait for a breach.
- The Adjustment: I will buy a long call at the 7000 strike.
- The Result: This converts the lizard into an Iron Condor. I spend a small portion of my $13.40 credit to “cap the tail,” defining my risk and dramatically reducing my margin requirement.
3. The “Nightmare Scenario”
A “Black Swan” gap down below 6500 would test the wings. Because the put side is a defined-risk spread, my loss is capped. My hard stop is an underlying price of 6480 or a VIX spike above 32.
Final Thoughts
The Jade Lizard is the ultimate “Stay in Your Lane” trade. It rewards the trader who realizes that the market’s bark (Implied Volatility) is almost always worse than its bite. I am sitting in the green zone, the clock is ticking, and the math is on my side.